Key Takeaways
- IUL policies blend life insurance protection with index-linked accumulation potential but require careful understanding of pros and cons.
- Expert guidance and a thorough needs assessment are crucial before considering IUL as part of your financial protection strategy.
Are you exploring new ways to balance life insurance protection with the potential for long-term growth? Indexed Universal Life (IUL) policies offer features unlike traditional coverage options. Let’s break down what an IUL investment truly means, clear up common misconceptions, and give you the essential information you need to make informed decisions.
What Is IUL Investment?
Definition of Indexed Universal Life
Indexed Universal Life, commonly referred to as IUL, is a type of permanent life insurance policy that combines traditional death benefit protection with a cash value component tied to a financial market index—most often the S&P 500 or similar benchmarks. Rather than directly investing in the stock market, your policy’s cash value grows based on interest credits linked to the performance of the selected index, subject to certain limitations.
How IUL Works in Financial Planning
An IUL policy offers two-fold value: insurance protection for your beneficiaries and the opportunity for tax-advantaged cash value accumulation over time. With its flexible structure, you can adjust premium payments within certain boundaries, and even access the built-up cash value to supplement objectives like retirement, emergencies, or legacy planning. This makes IUL a strategically versatile option within the broader landscape of financial planning.
Why Consider an IUL Policy?
Long-Term Protection Goals
You may seek life insurance that not only provides a death benefit for loved ones but also supports longer-term wealth-building. IUL policies meet this goal by allowing you to maintain lifelong coverage as long as premiums are kept up, and by growing a cash value balance that you can access under specific circumstances.
Tax-Advantaged Accumulation Basics
The cash value accumulation in an IUL grows tax-deferred, meaning you won’t owe income tax on these gains as long as they remain within the policy. Additionally, you can access this money through policy loans or withdrawals, often on a tax-advantaged basis, adding a layer of flexibility that can enhance your financial security and planning strategies. However, it’s crucial to monitor loan activity and policy values to avoid unintended tax consequences or policy lapses.
What Are the Key Pros of IUL?
Flexible Premium Structures
Unlike some traditional life insurance options, IUL policies allow you to adjust your premium payments within policy limits. You can choose to pay more when times are good to build cash value, or decrease (but not skip) premiums if needed, as long as the policy’s minimum requirements are satisfied. This adaptability can be advantageous as your financial circumstances evolve.
Index-Linked Interest Credit Features
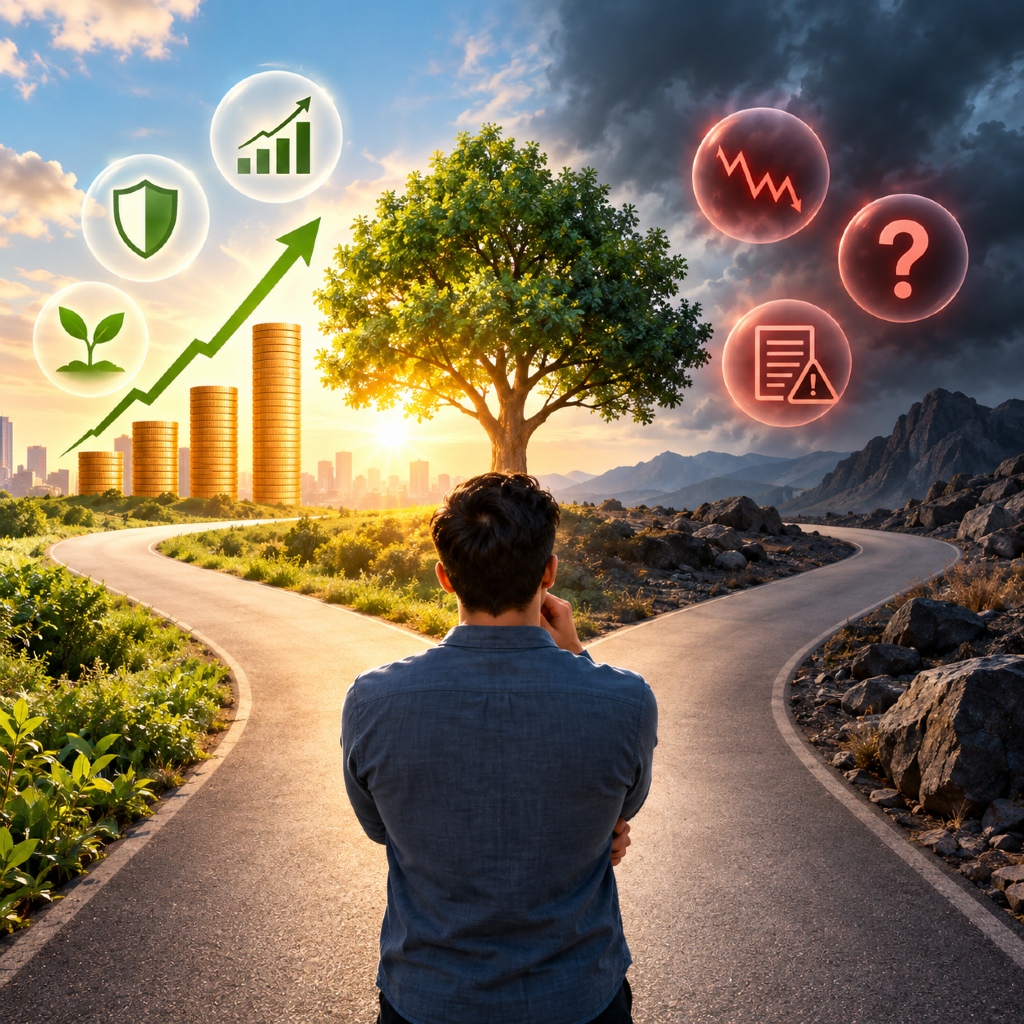
IUL policies credit your cash value with interest based on movements in a chosen market index. While this links potential growth to the performance of broader financial markets, you are generally protected from negative index changes. Instead of losses, your credited interest may simply be zero for a period if the market performs poorly. Some protection against downturns, combined with the potential for positive interest credits, offers a distinct appeal for those who value balance between safety and opportunity.
What Are the Common Cons?
Cost Considerations and Fees
IUL policies tend to have more complex fee structures than term or even some whole life insurance products. Charges can include cost of insurance, administrative expenses, and fees for any optional policy features. These costs may affect both your premiums and the accumulation of cash value, especially in the early years when charges often peak. It’s important to understand all policy charges before committing to an IUL.
Interest Crediting Limits
While IUL offers the possibility of earning interest based on index performance, it also has built-in caps and participation rates. These limits keep policy growth from mirroring the full return of the underlying index. For example, when markets perform very well, your credited interest may still be capped by a preset maximum. Conversely, on the downside, floors help protect against negative returns. Understanding these limitations is essential for realistic expectations.
Which Misconceptions Still Persist?
Guaranteed Returns vs Actual Outcomes
One prevalent misunderstanding is believing IUL policies offer guaranteed returns or a guaranteed stream of income. However, while there are built-in minimum interest crediting rates (often called “floors”), returns are never guaranteed to match any specific number. Actual credited interest will always depend on your policy’s structure and the performance of the referenced index, within the parameters set by the insurer. Avoid any expectation that an IUL policy eliminates all risk or uncertainty regarding growth.
Market Exposure and Risk Misunderstandings
Another misconception is assuming IUL cash value is directly invested in the stock market or fully protected from all risks. In reality, your cash value is not at risk of market loss in the same way as direct equity investments, but neither is it immune to the impact of fluctuating caps, participation rates, and policy fees. It’s important to understand that IUL is not an investment in the market, but an insurance policy with unique interest crediting features.
What Key Facts Should You Know?
Understanding Policy Flexibility
IUL stands out for its adjustability—both in terms of premium payments and death benefit, within policy limits and regulatory requirements. You must, however, maintain certain minimums to keep the policy active and to avoid penalties or unwanted lapses. This flexibility is empowering but requires careful, ongoing management.
Suitability and Professional Guidance
IUL isn’t right for everyone. It is best considered as one part of a comprehensive financial plan for those who value lifelong insurance coverage and are interested in tax-advantaged accumulation, while comfortable with policy complexity and variable interest credits. Always consult a qualified insurance or financial professional to analyze your needs before making commitment decisions.
Is IUL Right for Your Goals?
Assessing Personal Needs
Consider your long-term financial objectives, risk tolerance, family protection priorities, and the level of hands-on policy management you’re comfortable with. An IUL policy can be a valuable tool when these goals align, but clarity about your situation is essential.
Alternative Protection Strategies
There are other life insurance options, including term, whole, and other universal life policies, each with their unique strengths and trade-offs. Compare these alongside IUL to ensure you’re choosing a path that matches your protection, accumulation, and flexibility needs. It’s wise to examine all avenues in partnership with a trusted advisor.