Key Takeaways
- IUL Infinite Banking offers unique growth potential and tax advantages compared to traditional savings, but comes with complexity and suitability considerations.
- Choosing the right approach depends on your financial goals, need for access, tax preferences, and long-term planning outlook.
Are you curious about how innovative savings strategies compare to the accounts you’ve used for years? Discovering how IUL Infinite Banking measures up against traditional savings can be pivotal in shaping your financial future. Let’s break down the essentials so you can confidently align your savings strategy with your personal goals.
What Is IUL Infinite Banking?
Basic structure explained
IUL Infinite Banking is a concept that uses an indexed universal life insurance (IUL) policy to build cash value alongside life insurance protection. With IUL, you pay flexible premiums that accumulate cash value over time. This cash value is tied, via crediting methodologies, to a stock market index (such as the S&P 500), but with built-in protection features that prevent direct loss from negative index performance. The structure supports both a death benefit for loved ones and a growing cash value component you can access in certain ways during your lifetime.
How cash value accumulation works
Within IUL policies, a portion of your premium covers the cost of insurance, while the remainder goes into the policy’s cash value. This cash value, in turn, earns interest based on index movement using a crediting formula. Importantly, your cash value is not directly invested in the market, so you benefit from potential index gains up to a cap, but are protected from losses in negative years by a guaranteed floor, often set at zero. Over the long term, this allows for growth potential that is not reliant on constant positive market performance.
Role in financial strategies
IUL Infinite Banking is commonly positioned as a way to combine permanent life insurance with a flexible cash resource. The approach appeals to savers seeking tax-advantaged growth, flexible access to funds through policy loans, and financial protection for beneficiaries. In financial planning, this strategy may serve as a supplemental savings vehicle, funding for future opportunities, or as part of retirement planning for dependable access to cash value and tax diversification.
How Does Traditional Savings Work?
Types of savings accounts
Traditional savings methods include a variety of bank-based products, such as regular savings accounts, high-yield savings accounts, and money market accounts. These accounts offer safety, simplicity, and easy access to your money, making them a go-to for emergency funds or short-term goals.
Interest crediting basics
Banks pay you a modest rate of interest on your balances. The rate is typically fixed or variable, and influenced by the overall economic environment. The value of your savings grows predictably, though usually at a rate lower than long-term market-based investments. Federal insurance (such as FDIC coverage in the U.S.) often protects your deposits up to applicable limits.
Withdrawals and accessibility
A key benefit of traditional savings accounts is immediate liquidity. You can deposit and withdraw funds with minimal restrictions, making them ideal for unplanned expenses or goals you’ll reach within a few years. There are generally no penalties or complexity for accessing your own money, aside from standard account agreements.
What Are the Key Differences?
Growth potential and protection
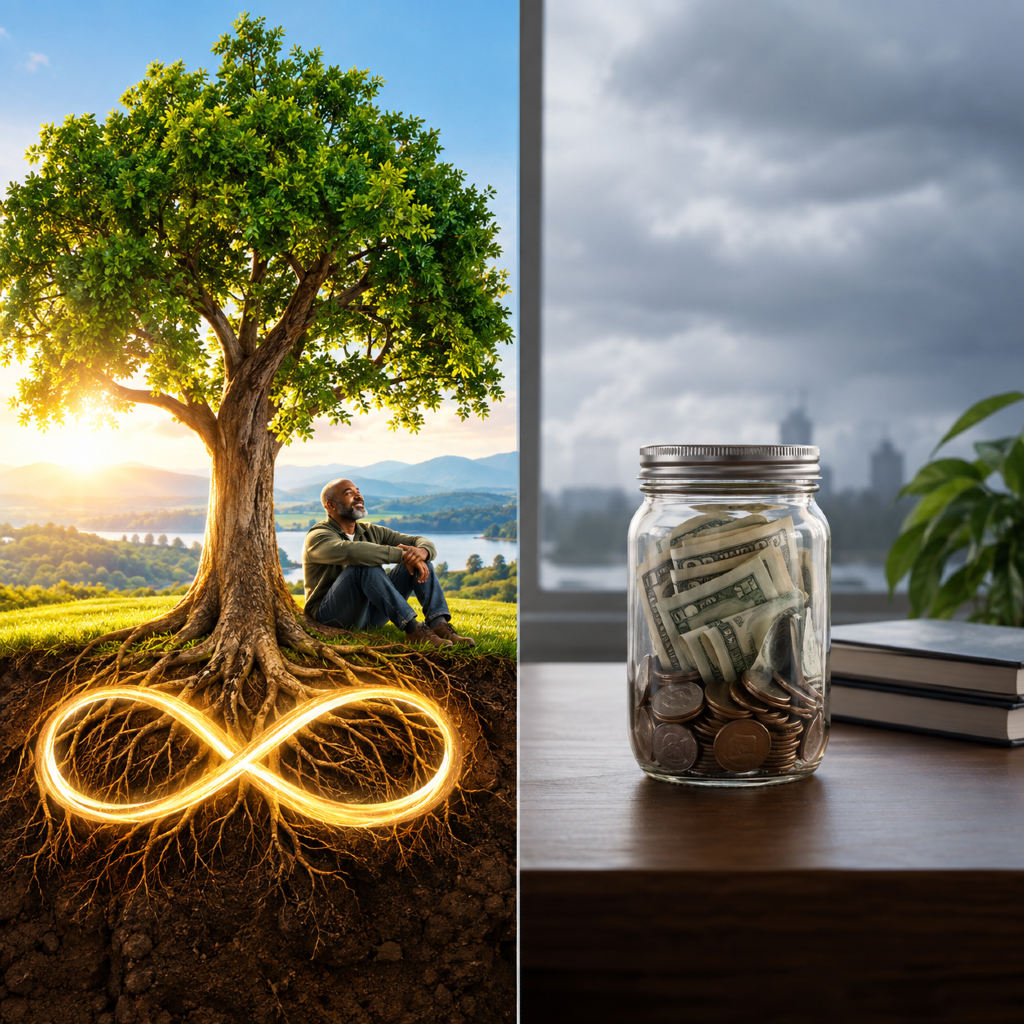
IUL Infinite Banking policies offer a potential for cash value growth based on credited interest linked to an index. While they offer a protective floor against losses, upside is limited by interest rate caps and policy costs. Traditional savings accounts grow steadily but at a typically lower rate, with minimal risk to principal. The trade-off here is between greater upside potential versus predictable, secure but modest returns.
Tax treatment differences
With IUL, policy growth is generally tax-deferred—meaning you won’t pay annual taxes on credited interest while the funds remain inside. Accessing cash value through policy loans may also be tax-advantaged, if the policy remains in good standing. Conversely, interest earned in traditional savings accounts is typically taxed as ordinary income annually, reducing your effective yield.
Accessing funds
Traditional savings accounts allow immediate, penalty-free withdrawals. With IUL policies, you may access cash value through policy loans or withdrawals, but you must follow certain guidelines. Loans accrue interest and must be managed to keep the policy in force. Accessibility is available, but not as instant or straightforward as with bank savings.
Pros and Cons of IUL Banking
Potential advantages
- Tax-deferred cash value growth and potentially tax-free policy loans
- Permanent life insurance protection for your heirs, adding estate and family planning value
- Protection against market downturns through policy structure (with a guaranteed floor)
- Access to accumulated cash value for personal or business funding needs
Possible limitations
- More complexity than traditional savings
- Policy charges and cost-of-insurance fees can impact growth
- Requires long-term commitment to realize full benefits
- Improper use of policy loans can risk the underlying policy if not managed carefully
Suitability considerations
IUL Infinite Banking strategies may suit you if you’re comfortable with a long-term horizon, seeking tax-advantaged growth, and value combining protection with cash accumulation. It might be less ideal if you’re seeking ultra-simplicity, very short-term liquidity, or if you prefer pure deposit guarantees.
When Might Traditional Savings Fit Best?
Situations for traditional savings
Traditional savings excel for your emergency funds, near-term purchases, or when you want full, unencumbered access to your money. They are fitting for anyone prioritizing safety, immediate liquidity, and maximum simplicity.
Short-term needs vs. long-term goals
While savings accounts are excellent for upcoming expenses, like vacations or household projects, they may fall short as standalone long-term growth solutions due to lower interest rates. For longer-term objectives, you might consider blending savings with other vehicles to harness both safety and growth potential.
Ease of use factors
Bank accounts are easy to open, manage, and understand. There’s minimal paperwork and no medical qualification, as may be required for life insurance. This ease makes them particularly attractive as your financial starting point.
Which Strategy Is Right for You?
Personal financial objectives
Before choosing between IUL, Infinite Banking, or traditional savings, reflect on your personal goals and timeline. Do you value guaranteed access, or are you interested in leveraging tax advantages with long-term protection? Consider how each approach supports your vision for building, preserving, and passing on wealth.
Questions to ask professionals
When considering more advanced strategies like IUL, consult with a licensed insurance professional. Important questions include: What are the potential risks and costs? How do cash value loans really work? Can this align with my broader financial plan? Their perspective can clarify whether the approach complements your priorities.
Balanced approach considerations
Many find that blending strategies yields effective results. You might keep a portion of funds in a traditional savings account for emergencies and short-term needs, while allocating resources towards IUL for longer-term protection, tax advantages, and growth potential. Striking a balance can help optimize both security and opportunity in your financial journey.