Key Takeaways
- IUL can provide both life insurance protection and opportunities for tax-advantaged cash value growth.
- Careful policy management and understanding of features are essential to maximize IUL benefits and minimize risks.
If you’re exploring ways to combine financial protection and long-term accumulation, Indexed Universal Life (IUL) insurance may be of interest. This guide covers how IUL works, what makes it unique, its potential benefits and risks, and how taxes apply. You’ll also find strategies for managing IUL effectively and key considerations before deciding if it’s right for your goals.
What Is Indexed Universal Life?
How IUL Policies Work
Indexed Universal Life (IUL) is a type of permanent life insurance. Like other universal life policies, it provides lifelong coverage as long as premiums are paid and the policy remains in force. What makes IUL distinct is how it offers the chance to build cash value linked to the performance of a market index, such as the S&P 500, but without direct market investment. Your payments help cover insurance costs, with the remainder allocated to the policy’s cash value.
Interest Crediting Explained
IUL policies credit interest to your cash value based on an external index’s movement. However, your policy’s account is not directly invested in the market. The insurer calculates the credited interest annually (or monthly), subject to a cap (maximum crediting rate) and a floor (minimum, often 0%). This helps protect against negative index returns while still allowing for some growth if the index performs well. Remember, credited interest will vary, and no specific rate is promised.
Flexibility and Policy Features
One of IUL’s most attractive features is flexibility. You can adjust premium payments and, within certain limits, increase or decrease your coverage. Over time, the cash value can be used for policy loans or withdrawals, though these will impact your policy’s performance and death benefit. Riders and options, such as living benefits, may also be available to tailor your coverage to individual needs.
Why Consider IUL for Planning?
Role in Financial Protection
At its core, IUL is a life insurance policy designed to provide a death benefit to your beneficiaries. This delivers financial protection for your loved ones, meeting needs such as debt repayment, education costs, or income replacement. The insurance element remains central, providing foundational security.
Potential for Tax-Advantaged Growth
One appealing characteristic of IUL is the opportunity for tax-advantaged accumulation. As your cash value grows, it does so on a tax-deferred basis. This means you won’t pay taxes each year on growth inside the policy. This feature can help you accumulate funds that may be used for various future purposes, like supplemental retirement income, provided you follow policy guidelines.
Long-Term Planning Strategies
Some individuals incorporate IUL as part of a comprehensive financial plan, using its cash value for long-term objectives such as education funding, legacy planning, or income supplementation. The combination of protection, flexible access, and potential for accumulation provides adaptability, especially if future needs change.
What Are the Main Benefits?
Protection with Accumulation Potential
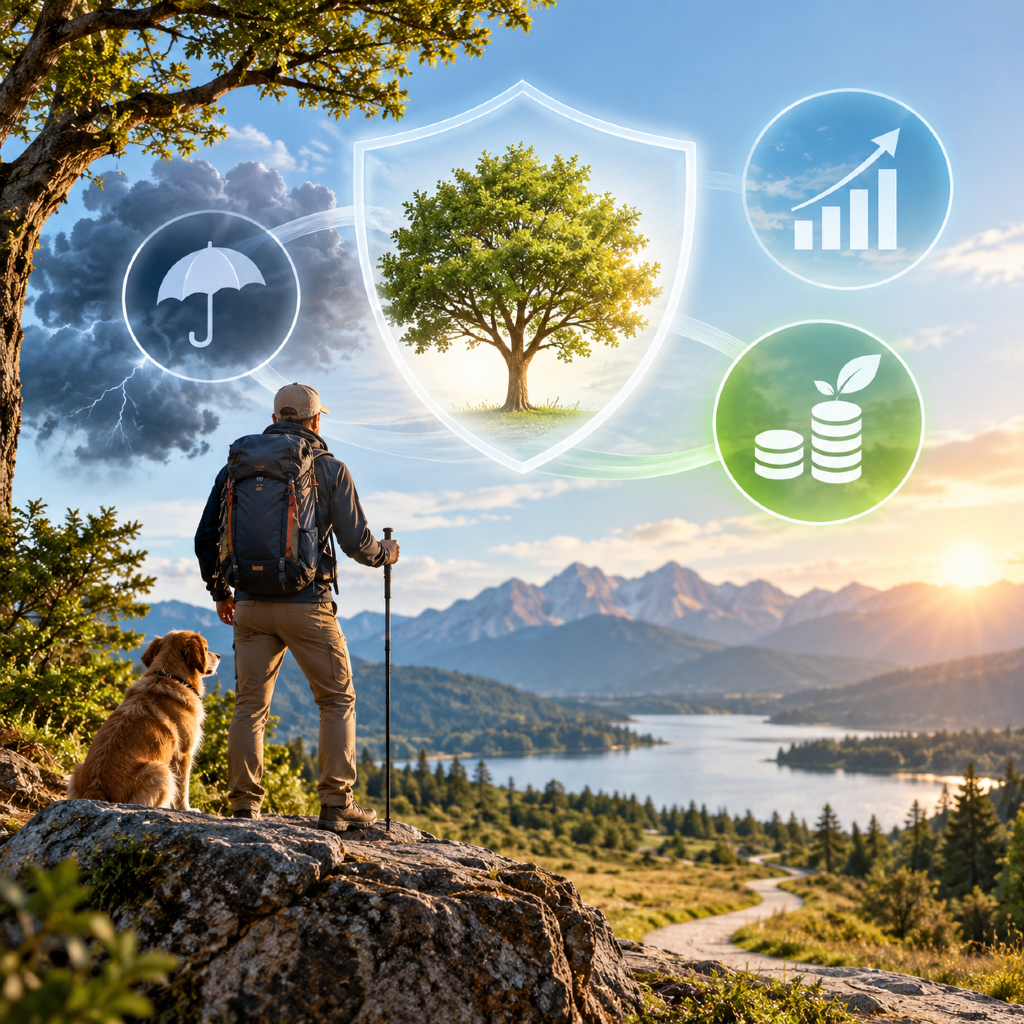
IUL offers dual benefits: a guaranteed death benefit and the possibility to grow tax-deferred cash value. While returns depend on index performance—and are subject to policy caps and floors—the policy gives holders a blend of protection and growth potential without direct market risk exposure.
Flexible Premium Options
You’re not locked into a fixed premium schedule. As long as you meet certain minimums and the policy cash value isn’t depleted, you can often adjust how much you pay and when. This feature is particularly useful during periods of changing income or financial priorities.
Inherited Value for Beneficiaries
Upon your death, the beneficiaries named in your policy receive the death benefit, generally income-tax free. This can be an important planning tool, allowing you to pass on value or provide for family members in the future.
What Risks Should You Know?
Interest Crediting Limits
While IULs provide downside protection (often a 0% floor), they also typically limit the upside with interest crediting caps and spreads. This means that if the index performs extremely well, your credited interest will be capped. Over long periods, this constraint can impact the accumulation potential compared to direct investments.
Cost of Insurance Over Time
The cost of insurance inside an IUL policy often increases as you age. If the policy’s cash value underperforms due to low credited interest or if premiums are insufficient, your policy may require additional funding to stay in force. It’s important to monitor the underlying costs and how they affect your policy over time.
Potential for Policy Lapse
An IUL can lapse (terminate) if policy charges and insurance costs are not covered by cash value or ongoing premiums. Lapse can result in loss of coverage and, in some cases, tax consequences. Understanding the factors that affect policy sustainability helps you manage the risk of lapse.
How Are IUL Policies Taxed?
Tax Treatment of Policy Growth
The cash value in an IUL grows tax-deferred. This means you won’t owe taxes on policy gains as long as they remain within the policy. Tax advantages apply as long as the policy maintains its favorable tax status (compliance with IRS rules for life insurance).
Loans and Withdrawals Considerations
You can generally access policy cash value through loans or withdrawals. Loans are typically not considered taxable income as long as the policy remains in force and is not classified as a modified endowment contract (MEC). Withdrawals may be tax-free up to your basis (the amount you’ve paid in premiums), but anything above that can be taxable. Improper management or a policy lapse with an outstanding loan can trigger unexpected taxes.
Beneficiary Tax Implications
Life insurance death benefits are typically passed income-tax free to beneficiaries. This makes IUL a viable strategy for legacy and estate planning. However, there may be exceptions in certain scenarios, such as if the policy is owned by a third party or in the case of a large taxable estate.
Best Practices for Managing IUL
Regular Policy Reviews
Regular reviews ensure your policy aligns with your expectations and continues to perform as planned. Review statements annually, paying attention to cash value growth, credited interest, and policy expenses. Life changes may warrant adjustments to coverage, beneficiaries, or funding levels.
Aligning with Financial Goals
Periodically evaluate how your IUL supports your financial goals. Life events—like marriage, home purchase, or nearing retirement—can affect your needs. Keeping your policy aligned with your big-picture objectives maximizes its usefulness.
Working with Financial Professionals
A licensed insurance or financial professional can help you understand policy options, review features, and monitor ongoing suitability. Regular communication with a knowledgeable advisor supports informed decisions and helps you stay current with changing rules or tax laws.
Is IUL Right for Everyone?
Evaluating Your Needs
IUL is a flexible planning tool but it’s not suitable for every individual or family. Consider your risk tolerance, long-term protection needs, liquidity requirements, and comfort with potential policy cost fluctuations before deciding.
Considering Alternative Options
Compare IUL to other solutions, such as term life, whole life, or variable universal life insurance, as well as non-insurance instruments for savings or investment. Each offers unique benefits and trade-offs. The most effective choice aligns with your personal priorities and financial picture.