Key Takeaways
- Life insurance can help protect the people who depend on you. Its value depends on choosing coverage that fits your needs and keeping the policy active.
- Before you buy, weigh the benefits against premium payments, coverage limits, cash value rules, and the terms your beneficiaries must meet.
How Does Life Insurance Work?
Life insurance is an agreement between you and an insurer. You pay premiums to maintain coverage. If you die while the policy is active, your chosen beneficiaries can receive a payment called a death benefit, subject to the policy’s terms.
Your beneficiaries are the people or entities you name to receive that payment. They must submit a claim and the required documents. Naming them clearly and keeping their details current helps support that process.
Before approving your application, an insurer may review your health, medical history, and other personal details. Answer each question fully and honestly. Missing or false information can affect coverage or a claim.
Understanding how life insurance works starts with a simple question: what financial gap would your death leave? Your answer should guide your coverage choice.
Which Life Insurance Benefits And Drawbacks Should You Weigh?
Life insurance can support your financial plans, but every feature comes with limits. These five areas help you assess whether a policy serves your needs.
1. How Can Life Insurance Protect Your Household?
Benefit: Your death benefit can give your beneficiaries financial support when they lose your income or unpaid care. It can help them manage household needs without relying only on savings.
When assessing your needs, consider:
- Income your household depends on.
- Care and household tasks you provide.
- Financial commitments you want to support.
- Savings and other resources already available.
Drawback: Coverage may fall short if you overlook part of your contribution. A policy that once suited your household may also become less suitable as your needs change.
You should review the purpose of your coverage when your responsibilities change. Buying life insurance is only part of protecting your household. Keeping the protection aligned with your needs matters too.
2. How Can A Death Benefit Support Financial Commitments?
Benefit: Life insurance can provide funds your beneficiaries may use for living expenses, final expenses, or other needs. This gives them room to make financial choices during a difficult situation.
Your planning should reflect the obligations you want to address. Think about shared responsibilities and whether others would struggle to meet them without your support.
Drawback: A death benefit does not automatically settle every obligation. The policy pays according to its terms and beneficiary instructions. Your wishes alone may not control how the money is used.
You should also avoid assuming that every debt becomes your family’s responsibility. Debt obligations depend on the circumstances. Keep your insurance planning connected to your broader financial and estate plans.
3. How Do Term Life Insurance And Permanent Life Insurance Compare?
Benefit: Different coverage types let you match life insurance to your purpose. Term life insurance provides protection within a defined coverage term. Permanent life insurance is designed to remain in force while its requirements are met.
Your choice should begin with the need you want to cover. A clear purpose makes it easier to judge whether added features are useful.
Drawback: Neither type removes the need to understand the contract. Term coverage can end. Permanent coverage can lapse if you fail to meet its funding requirements.
Ask these questions before choosing:
- What must you do to keep coverage active?
- Can required payments or benefits change?
- Which policy features are guaranteed?
- What happens if you cancel or change coverage?
Choose based on the protection you need and the obligations you can maintain.
4. What Does Cash Value Add To Life Insurance?
Benefit: Some permanent life insurance policies include cash value. Depending on the contract, you may access it through withdrawals or policy loans. This feature can offer flexibility while you are alive.
However, cash value and the death benefit serve different purposes. Understand how each works before treating the policy as part of your savings strategy.
Drawback: Accessing cash value can reduce what your beneficiaries receive. Loans can carry interest, and withdrawals or unpaid loans can weaken the policy. Surrendering coverage may involve charges.
You should not assume that cash value is freely available or paid in addition to the death benefit. Ask which values are guaranteed and which depend on policy performance. Also ask how taking money out affects your coverage.
5. How Can Life Insurance Support Your Peace Of Mind?
Benefit: A suitable policy can help you feel more prepared. Knowing that you have arranged financial support can make your protection plan clearer.
You can strengthen that plan by keeping policy records accessible and telling your beneficiaries how to locate them. Clear information helps them understand what steps to take when making a claim.
Drawback: Peace of mind can become false confidence if you overlook exclusions or payment requirements. Owning a policy does not mean every claim will qualify.
Read the contract carefully. Ask about exclusions, reasons a claim could be denied, and what happens after missed payments. Pay attention to required premiums as well. Coverage should fit your budget without placing essential needs under strain.
What Should You Check Before You Buy Life Insurance?
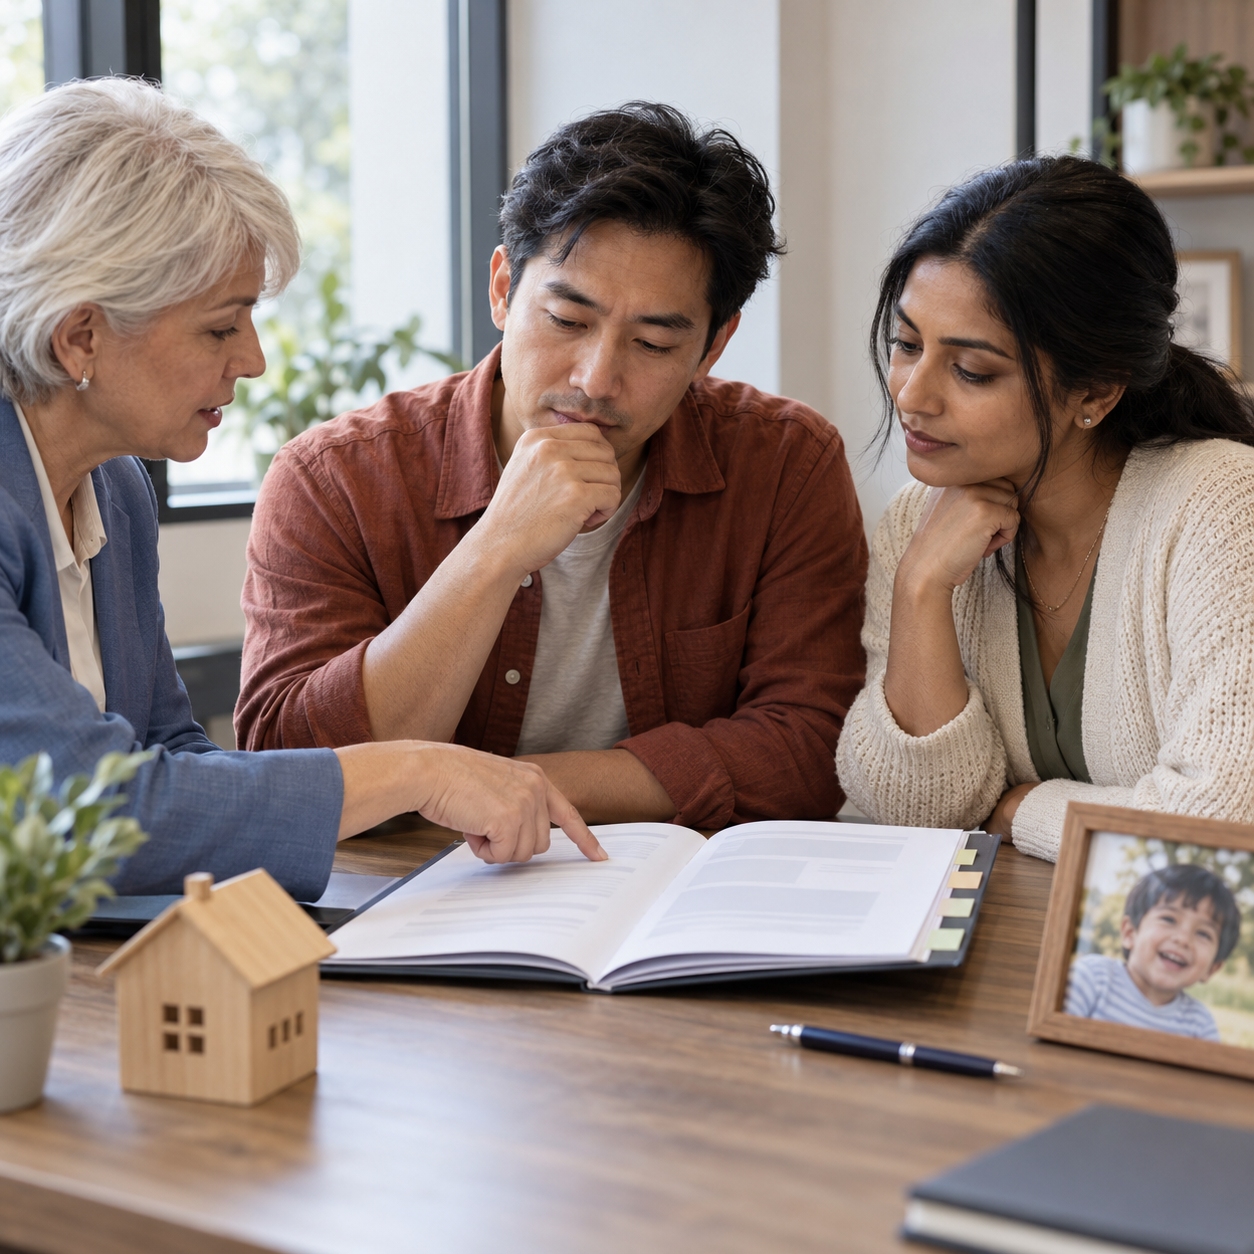
Start with your household’s needs, then compare policy features against them. Avoid choosing coverage based only on a headline benefit or a sales summary.
Make sure you understand:
- Who receives the death benefit.
- What keeps the policy active.
- Which exclusions and limits apply.
- Whether optional benefits serve a clear purpose.
- How cancellation affects coverage and cash value.
Ask for plain explanations of unclear terms. You should understand what you are agreeing to before signing.
Make A Clear Life Insurance Choice
Life insurance works best when its purpose is clear. Weigh protection, flexibility, and peace of mind against the payments and rules you must manage.
Choose coverage you understand and can maintain. Sign up on this website to explore more insurance guidance and make informed decisions about protecting those who depend on you.