Key Takeaways
- Your indexed universal life insurance can earn interest linked to market gains, but policy rules limit how much growth you receive.
- A crediting floor can protect against negative index returns. Your cash value can still decline because of policy charges, loans, or withdrawals.
Understanding Indexed Universal Life Insurance
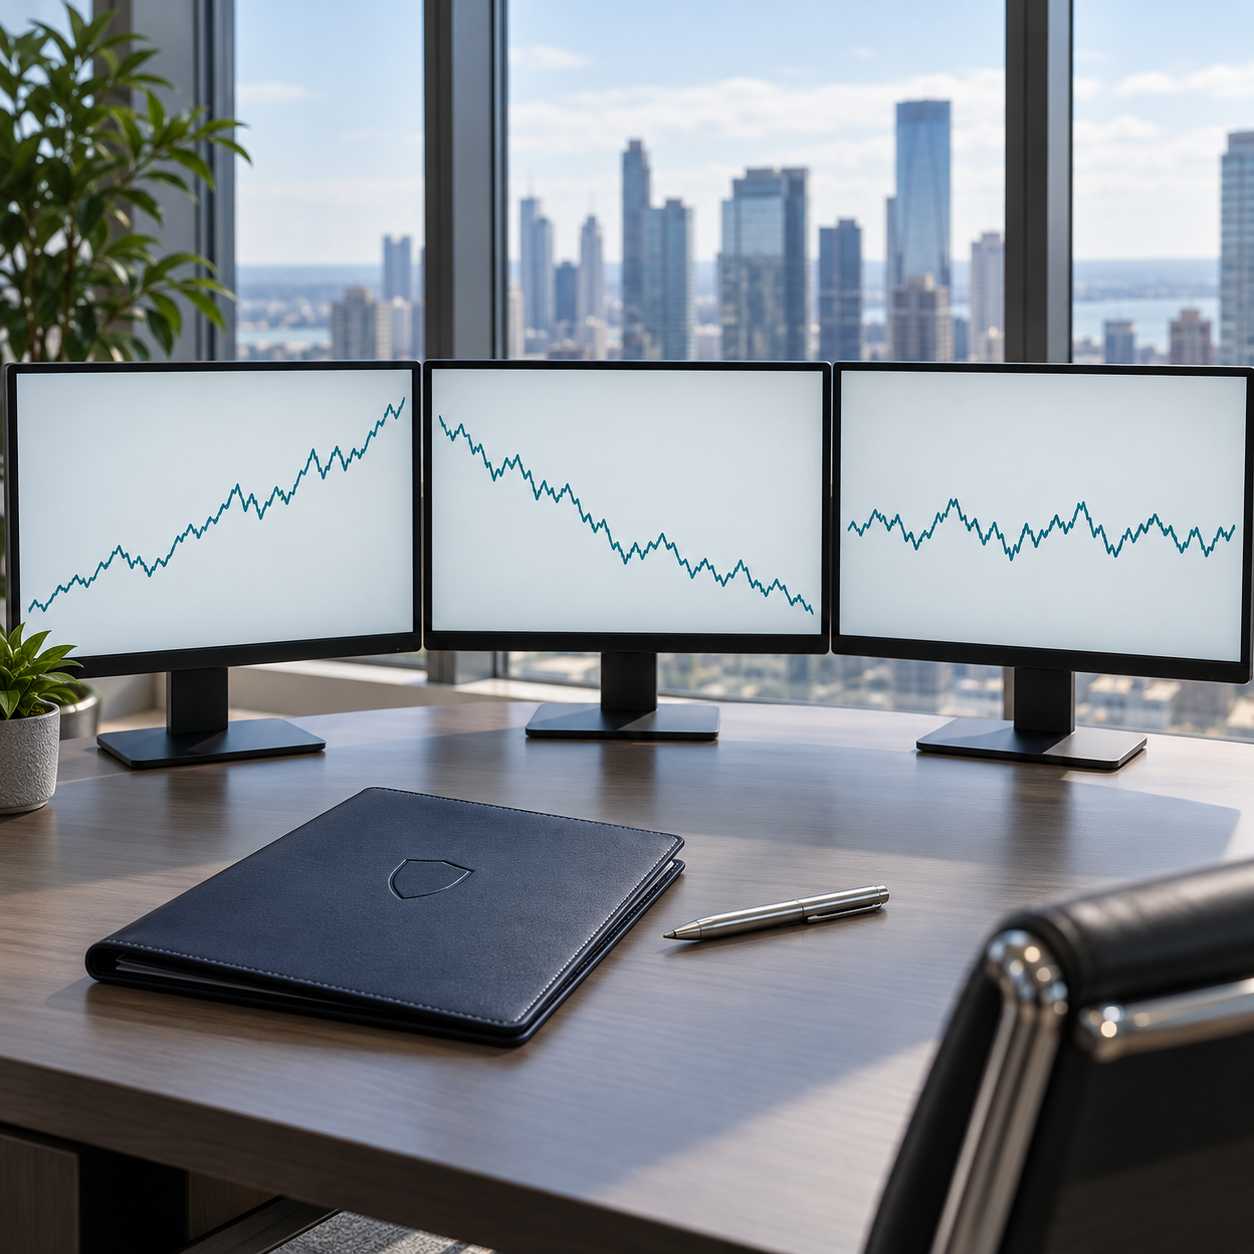
When you consider indexed universal life insurance, you need to understand how market changes affect your coverage and cash value. Rising markets can support growth. Falling or flat markets can reduce the interest credited to your policy.
However, your policy does not follow the market directly. Its terms determine how index performance becomes credited interest. Your payments, policy charges, and use of cash value also shape the result.
Understanding these moving parts helps you judge whether IUL insurance suits your needs. It also helps you avoid treating possible growth as a promise.
How Does Indexed Universal Life Insurance Work?
Indexed universal life insurance is a form of permanent life insurance. It combines a death benefit with cash value that can earn interest based partly on a market index.
Your beneficiaries receive the death benefit according to your policy terms when you die, provided your coverage remains active.
Your cash value serves a different purpose. It supports the policy and may give you access to funds through loans or withdrawals, subject to contract rules.
You do not own the stocks within the index through your policy. Instead, the index acts as a reference for calculating interest. Your cash value therefore does not receive the same return as a direct stock investment.
Indexed Universal Life Insurance In Rising Markets
A rising market can create an opportunity for cash value growth. However, a strong index gain does not mean your policy receives that full gain.
Your indexed account follows a crediting formula. Understanding that formula helps you set realistic expectations.
What Limits Your Interest Credits?
Several terms may affect how much interest your indexed account receives:
- Cap: The highest interest rate your account can receive under the applicable crediting rules.
- Participation Rate: The share of the measured index gain used to calculate your credit.
- Spread: An amount deducted from the index return when calculating credited interest, if applicable.
- Crediting Method: The rules used to measure index changes and apply the formula.
These features vary by contract and account option. Some terms may change within the limits stated in your policy.
Ask which terms are guaranteed and which can change. Also ask how they work together. Looking at a cap or participation rate alone may give you an incomplete view.
Does Market Growth Always Increase Your Cash Value?
Credited interest and net cash value growth are different.
Your policy deducts charges for insurance coverage, administration, and any added benefits. Loans and withdrawals can also affect the value available to support coverage.
Even when your account earns interest, those deductions may offset some or all of the gain. Review the change in your cash value after charges, rather than focusing only on the credited rate.
Indexed Universal Life Insurance In Falling Markets
When markets fall, your indexed account may receive little or no interest. A crediting floor sets the minimum interest credit under the account’s rules.
That feature can limit the effect of a negative index return. It does not protect your entire policy value from every source of loss.
Can Your Cash Value Still Decline?
Yes. A floor applies to the interest calculation, while policy charges remain separate.
Your cash value may decline when charges exceed credited interest and funds added through premiums. Outstanding loans and withdrawals can place further pressure on the policy.
This distinction matters when you hear claims about downside protection. You should understand exactly what the contract protects.
Ask your insurance professional to explain:
- How the floor applies to your indexed account.
- Which charges continue when interest credits are low.
- How weak performance affects the funding needed to maintain coverage.
Indexed Universal Life Insurance In Flat Markets
A market that goes nowhere can still affect your policy. Without enough measured index growth, your indexed account may earn little or no interest.
Meanwhile, the policy continues to provide insurance coverage and deduct its charges.
Why Does A Flat Market Matter?
Flat markets can reduce the cash value growth you expected. If your funding approach depends heavily on strong interest credits, weaker results may create a gap.
Flexible premiums do not mean that any payment amount will keep your coverage active. Your policy needs enough funding to meet its requirements.
You may need to adjust premiums, reconsider withdrawals, or review available benefits. The right response depends on your contract and financial situation.
Focus on whether your coverage remains properly funded when growth is limited.
Managing Your IUL Insurance Across Market Conditions
You cannot control market direction. You can control how carefully you review your policy and how much you rely on uncertain growth.
A sound approach starts with your need for life insurance.
What Should You Check In A Policy Illustration?
A policy illustration shows how coverage and cash value might develop under stated assumptions. Projected results are not promises.
Review guaranteed values separately from values based on assumptions that can change. Request illustrations showing weaker interest credits and the effect of policy charges.
Check how loans, withdrawals, and premium changes affect coverage. Ask whether any coverage guarantee has separate conditions you must meet.
How Should You Approach Loans And Withdrawals?
Accessing cash value can affect both your policy’s funding and death benefit. Loans also involve interest and contract rules that you need to understand.
Borrowing does not make growth certain, and withdrawing funds leaves less value inside your policy.
Before using cash value, review how reduced growth could affect your ability to maintain coverage. Ask about possible tax consequences as well.
Make An Informed Coverage Decision
Indexed universal life insurance works best when you understand both its growth potential and its limits. Review your funding needs, read the guarantees, and ask clear questions before deciding. Sign up on this website for insurance guidance that helps you make informed choices.