Key Takeaways
- An IUL policy calculator helps you visualize how indexed universal life insurance may align with your long-term financial goals.
- This tool can build your financial literacy and help you discuss options with qualified professionals.
Most Americans underestimate how much life insurance can affect their long-term financial plan—discover how an IUL policy calculator highlights those possibilities. Whether you’re new to indexed universal life insurance or want to see its potential role in your retirement strategy, understanding these calculators is the first step toward confident decision-making.
What Is an IUL Policy Calculator?
Purpose of an IUL calculator
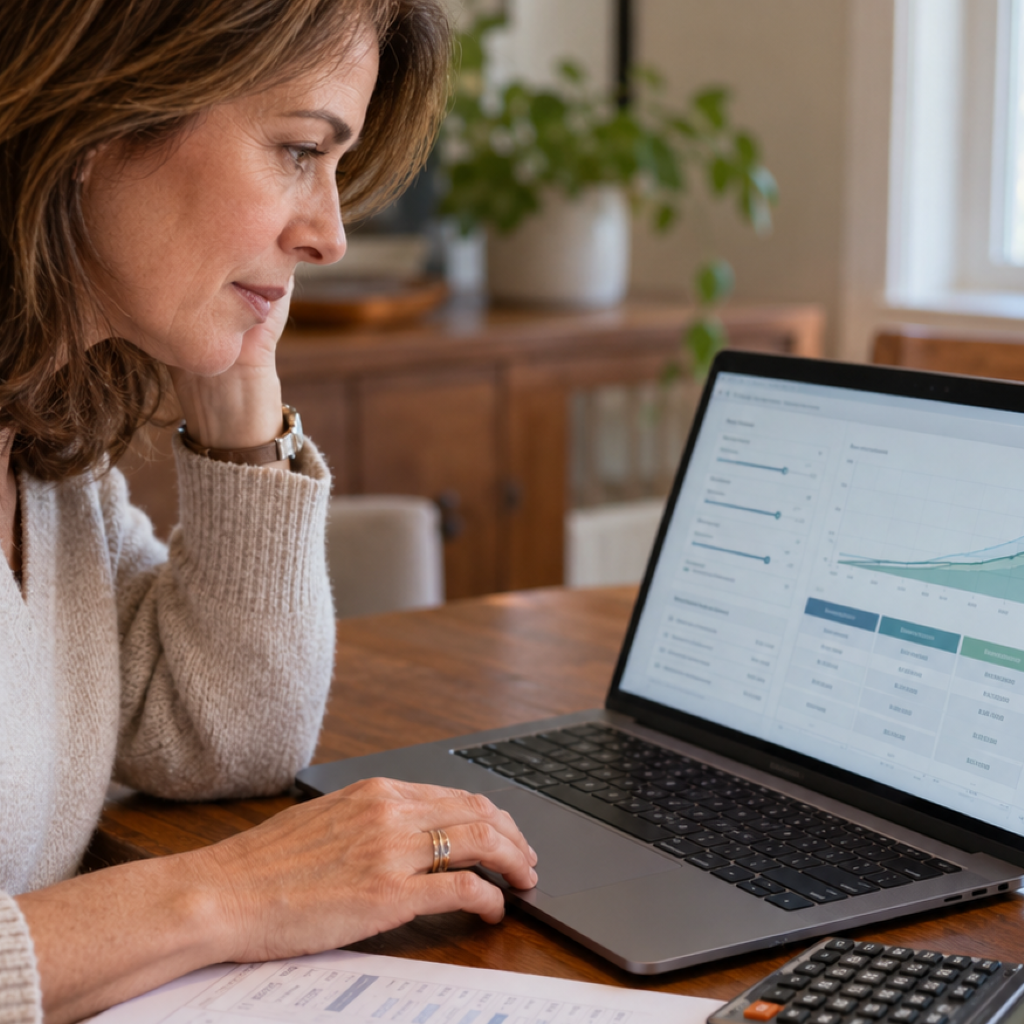
An IUL (Indexed Universal Life) policy calculator is an interactive tool designed to estimate how an indexed universal life policy could perform based on your unique financial profile and planning needs. Rather than offering specific investment advice, it provides you with a clearer understanding of how various choices—such as premium amounts and policy features—may influence policy performance over time.
How it aids financial understanding
This calculator demystifies complex life insurance concepts. By modeling hypothetical scenarios, it shows how indexed crediting mechanisms, payment flexibility, and potential cash value accumulation might look for someone in your situation. It’s an educational resource that encourages deeper engagement with your financial planning process and equips you with examples to discuss with your insurance or financial professional.
How Does an IUL Calculator Work?
Key inputs and assumptions
An IUL calculator typically requests information tied to your age, health, desired coverage amount, premium schedule, and risk preferences. It also uses assumptions based on historical data and general market trends, without guaranteeing or promising future results. The calculator may simulate how your premiums could accumulate value, how policy costs may play out, and how different indexing methods might impact credited interest.
Overview of calculation process
After you input your details, the calculator generates a projection of policy values over time using modeled assumptions. It may show potential growth in the policy’s cash value under several scenarios, illustrate policy charges, and account for the flexibility inherent in IUL products. Keep in mind that all output is intended to be illustrative—helping you better grasp how varying strategies or parameters might influence long-term planning, not predicting actual outcomes.
How Can It Illustrate Accumulation Potential?
Explaining index-linked interest crediting
One distinguishing feature of IUL policies is index-linked interest crediting. Rather than guaranteeing a fixed rate, credited interest is typically tied (in a formulaic and capped way) to a major financial index’s performance. An IUL calculator demonstrates possible outcomes tied to hypothetical index returns—within preset boundaries—to help you see how cash value could accumulate in favorable or less favorable market environments.
Demonstrating growth concept examples
Using clear visualizations, the calculator can show side-by-side scenarios, for example, how policy values evolve if the market performs above or below historical averages. While these are not promises, these models can strengthen your ability to understand both the growth opportunities and the inherent limitations of index-linked crediting strategies.
Clarifying Policy Structure and Flexibility
Visualizing premium options
Many find life insurance terminology intimidating, especially when it comes to premium flexibility. The IUL calculator makes these concepts easier to understand by letting you test different premium payment amounts, schedules, and durations. This can show how smaller or larger premium contributions may affect potential cash value and the policy’s long-term sustainability.
Customizing coverage for life stages
Life isn’t static, and your needs may change as you raise children, approach retirement, or support aging parents. The calculator helps you see how adjusting coverage levels or premium strategies can match evolving financial obligations at different life stages. This dynamic modeling encourages ongoing engagement with your life insurance plan and supports contingency planning.
How Does It Help With Tax Considerations?
Understanding tax-deferred accumulation
One of the core attractions of indexed universal life is its potential for tax-deferred cash value accumulation. The calculator can help illustrate how this works: as your policy’s value grows, you typically do not pay taxes on the accumulating portion as long as funds remain inside the policy. This feature is especially relevant for those considering long-term growth or eventual supplemental income in retirement.
Highlighting tax-related policy features
IUL calculators can also show other tax advantages linked to permanent life insurance, such as potential income-tax-free death benefits (when structured under current tax law) and tax-advantaged withdrawals or loans under qualifying conditions. These modeled features are conceptual, prompting you to consider how they could complement your broader financial plan if your situation warrants it.
Supporting Long-Term Financial Planning Goals
Projecting policy alignment with retirement
A major benefit of using an IUL calculator is the ability to model how a policy could supplement retirement income. By projecting hypothetical cash value and showing how life insurance protection and income strategies interact, the calculator shows how an IUL may align with other retirement resources. This can help you see how the policy could serve as a flexible part of your financial safety net.
Modeling legacy planning concepts
Beyond retirement income, legacy planning motivates many. IUL calculators can help demonstrate how a permanent death benefit or policy cash value might support wealth transfer goals or charitable giving as part of your estate plan. Again, these illustrations provide context and clarity so you can have productive discussions with estate planners or other advisors.
What Are the Limitations of IUL Calculators?
Factors not captured in calculators
While these calculators are powerful educational aids, they cannot account for every scenario. They may not reflect specific changes in tax laws, carrier charges, economic shifts, or personal health events that could alter real-world outcomes. Additionally, the calculator can’t account for non-financial factors—such as personal goals, family needs, or evolving priorities.
Importance of seeking professional guidance
An IUL policy calculator should serve as a starting point, not a substitute for professional advice. You’re encouraged to share your modeled results with a licensed insurance or financial professional who can offer individual guidance tailored to your unique situation. Their expertise ensures that your policy decisions are informed, compliant with regulations, and aligned with your overall planning objectives.